For most people, rebalancing a 401(k) once a year is enough, and a common refinement is to rebalance sooner if your mix drifts 5 percentage points or more from its target. That’s close to what Vanguard’s research suggests, and it’s the kind of check Astor, a personal investing agent, can run on a schedule across the accounts you connect, while every rebalancing decision stays yours.
Rebalancing isn’t about squeezing out more return. It’s about keeping the risk you carry close to the risk you chose. Below is what rebalancing means, the two ways to time it, how to do it inside a 401(k), and when it’s worth looking outside your usual schedule.
What does rebalancing a 401(k) actually mean?
When you picked your 401(k) funds, you chose a mix, say 80% stock funds and 20% bond funds. That’s your target allocation. Different investments grow at different rates, so the mix moves on its own. After a stretch where stocks outpace bonds, an 80/20 portfolio can quietly become 88/12, which means more of your retirement money is riding on stocks than you decided.
Rebalancing is bringing the mix back to that target. The SEC’s investor education office describes it as making sure your portfolio doesn’t lean too heavily on one asset category, so your risk goes back to a level you’re comfortable with. In practice, it means trimming whatever has grown past its share and adding to whatever has fallen behind. Investor.gov notes this can feel uncomfortable, because you’re cutting back on recent winners to add to recent laggards.
It helps to separate rebalancing from reallocating. Rebalancing returns you to the target you already have. Reallocating changes the target, for example moving from 80/20 to 70/30 as retirement gets closer. Investor.gov says a change in your time horizon is the most common reason to change your allocation, along with changes in your risk tolerance, finances or goals.
Should you rebalance on a calendar or when your mix drifts?
Investor.gov describes two approaches. With a calendar approach, you rebalance at a regular interval, and it says many experts suggest every six or twelve months. With a threshold approach, you rebalance only when an asset class moves more than a percentage you picked in advance. Either way, it says rebalancing tends to work best when you do it relatively infrequently.
Vanguard lands on the calendar side for most people. Its investor education page says that for many investors an annual rebalance is optimal, and that the key is picking a schedule that’s easy to follow. A Vanguard research paper by Colleen Jaconetti, Yan Zilbering and Francis Kinniry combined the two ideas. It concluded that checking annually or semiannually and rebalancing when an asset class is 5% or more off target is likely to strike a reasonable balance between controlling risk and keeping costs down for most investors. The same research found there’s no single best frequency or threshold, so treat 5 points as a common rule of thumb, not a law.
| Calendar | Threshold | Calendar plus threshold | |
|---|---|---|---|
| When you act | On a set date | When your mix drifts past a band you chose | On a set date, only if the mix is past the band |
| Example | Every January | Stocks more than 5 points off target | Check every January, act only if 5 or more points off |
| Upside | Easy to remember | You act only when drift is meaningful | Few trades, and drift stays limited |
| Downside | You may trade when little has changed | You have to check often | Drift can build between checks |
How do you rebalance inside a 401(k)?
Investor.gov lists three basic ways to rebalance, and all three work inside a 401(k).
- Exchange between funds. On your plan’s website, move part of the fund that has grown past its share into the fund that has fallen behind. Inside the plan, this doesn’t trigger tax, because the IRS taxes 401(k) money, including earnings, when it’s distributed (qualified Roth distributions are the exception).
- Redirect new contributions. Change your contribution election so more of each paycheck goes to the underweight fund. Nothing gets sold, and the mix moves back gradually. This works best when the drift is small compared with what you contribute.
- Turn on automatic rebalancing, if your plan offers it. Some plans let you pick a target mix and a rebalancing schedule. Your plan’s website or summary plan description will say whether yours does. Keep in mind it only covers that one plan.
Before you trade, check whether your plan charges fees or limits how often you can move money between funds. Investor.gov suggests checking whether a rebalancing method will trigger transaction fees or tax consequences before you use it.
What if you’re in a target-date fund?
Investor.gov explains that the managers of a lifecycle, or target-date, fund make all the decisions about asset allocation, diversification and rebalancing, and the fund shifts toward a more conservative mix as its target date approaches. If your whole 401(k) sits in one target-date fund, there’s nothing to rebalance inside it. If you hold a target-date fund alongside other funds, though, the combined mix is yours to watch, because the fund only rebalances itself.
When should you check outside your usual schedule?
A yearly check covers most situations, but a few events are worth an extra look.
- A big market move. A sharp rise or fall can push your mix past your band faster than usual. Rebalancing after a drop means adding to what fell, which is sticking to your plan rather than predicting what happens next.
- A life change. A new job, marriage, a child or retirement getting closer can change how much risk makes sense. That’s usually a question about your target, so it’s a reallocation, not just a rebalance.
- Money moving in or out. Rolling an old 401(k) into a new plan or an IRA is a natural moment to land on your target. When you’re taking money out, Vanguard suggests withdrawing from the asset classes that are overweight, and it applies the same idea to required minimum distributions, which the IRS says generally start at age 73.
What about the money outside your 401(k)?
Plenty of people have more than one account, like a current 401(k), an old one from a previous job, an IRA and a brokerage account. Your plan’s rebalancing tool only sees that plan, but the risk you actually carry is the mix across all of them.
One common approach is to set a target for everything together and do most of the adjusting inside tax-advantaged accounts like a 401(k) or IRA, where moving between funds doesn’t create a tax bill. In a taxable brokerage account, selling an investment that has gained value can mean paying capital gains tax, so people there often lean on new money and dividends to rebalance instead. This is general education, not tax advice.
How Astor helps you keep track
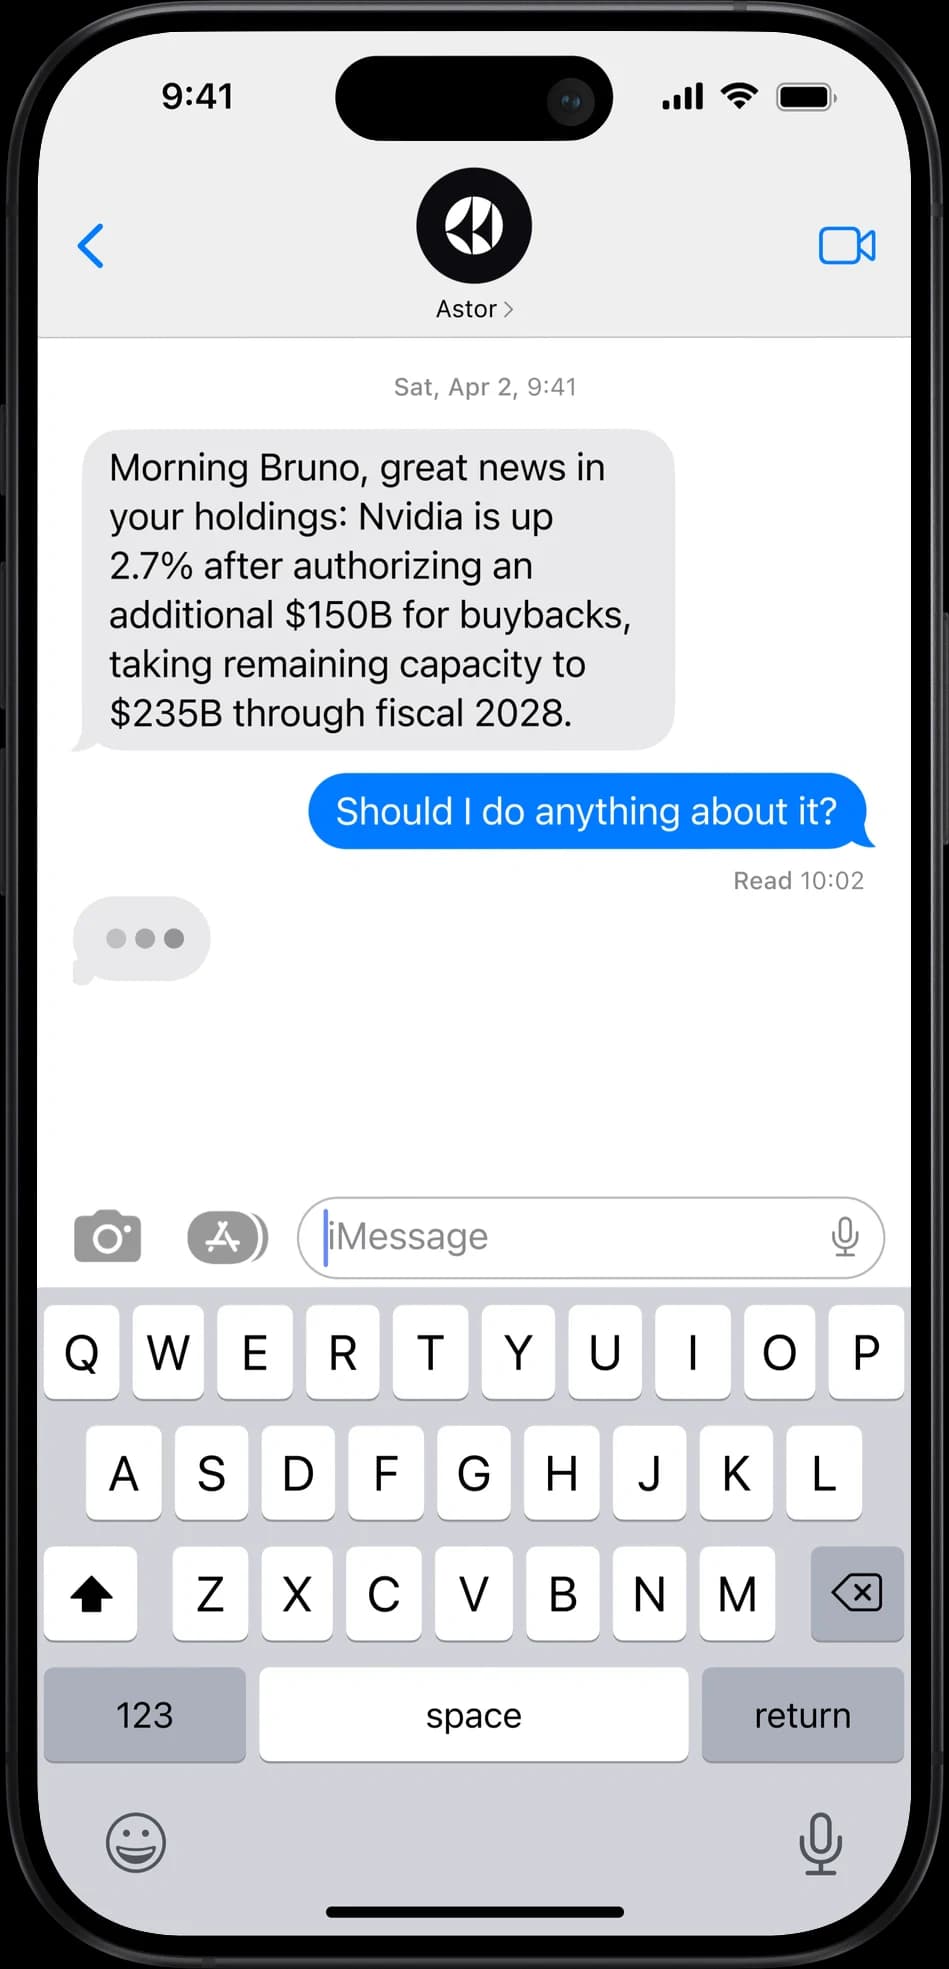
Astor is a personal investing agent on iPhone and in iMessage, and the company behind it, Gaus, Inc. DBA Astor, is an SEC-registered investment adviser. It connects through Plaid to brokerage, retirement and crypto accounts at most major US institutions, like Robinhood, Schwab and Coinbase, and learns what you own across all of them. That means you can ask it how your stock and bond mix looks across your 401(k), IRA and brokerage account together, and follow up in the same thread.
With scheduled alerts, you can ask Astor to check something on a schedule or when a condition is met. A hypothetical example would be “every January, tell me whether my stock share across all my accounts is more than 5 points off 80%.” Astor texts you what it found, with the reasoning and sources behind it.
Astor can see your holdings, but it can’t move money or trade in the accounts you connect, and it doesn’t manage or rebalance anything. If you decide to rebalance, you do it in your plan or brokerage. The AI can be wrong, which is why it shows its sources and you make the call. Astor is free to start, and you can see how it works.
Frequently asked questions
How often should I rebalance my 401(k)?
For most people, once a year is enough. Vanguard says an annual rebalance is optimal for many investors, and a common refinement is to rebalance sooner if your mix drifts 5 percentage points or more from its target. Pick a schedule you’ll actually stick to.
Is it bad to rebalance too often?
It isn’t harmful in itself, but it usually adds trades without much benefit. Vanguard warns against rebalancing too frequently, and Investor.gov says rebalancing tends to work best when done relatively infrequently.
Should I rebalance during a market drop?
If a drop has pushed your mix past your band, rebalancing means adding to the asset that fell to get back to your target. That’s following the plan you already set, not a forecast. Whether to do it is your decision, and if the drop has changed how much risk you’re comfortable with, that’s a question about your target allocation.
Do target-date funds rebalance automatically?
Yes. According to Investor.gov, the managers of a target-date fund handle asset allocation, diversification and rebalancing, and the fund gets more conservative as its target date approaches. If you hold other funds alongside it, you still need to watch the combined mix.
Does rebalancing a 401(k) have tax consequences?
Moving money between funds inside a 401(k) doesn’t create a tax bill, because the IRS taxes plan money when it’s distributed, and qualified Roth distributions aren’t taxed. Rebalancing in a taxable brokerage account is different, since selling can realize capital gains.
Sources
- Vanguard: Rebalancing your portfolio, how to rebalance, accessed Oct 21, 2026
- AAII Journal: Best Practices for Portfolio Rebalancing, by Colleen M. Jaconetti, Yan Zilbering and Francis M. Kinniry of Vanguard (May 2011), accessed Oct 21, 2026
- Investor.gov (SEC): Beginners’ Guide to Asset Allocation, Diversification, and Rebalancing, accessed Oct 21, 2026
- IRS: 401(k) plans, accessed Oct 21, 2026
- IRS: Retirement topics, required minimum distributions (RMDs), accessed Oct 21, 2026
Important information
Gaus, Inc. DBA Astor is an SEC-registered investment adviser (CRD #338424). Registration does not imply a certain level of skill or training. Astor provides non-discretionary advice: you make every investment decision. All investing involves risk, including the loss of principal, and past performance does not guarantee future results. Astor uses AI, which can make mistakes. This article is general information, not individualized investment, tax or legal advice. See our disclosures.
About comparisons
Information about other companies comes from their public websites and filings as of October 2026 and may have changed since; check each provider for current details. Comparisons and rankings reflect Astor’s opinion. Other companies’ names and trademarks belong to their owners, and no affiliation or endorsement is implied.
Share