You create a financial plan by writing down where you stand, deciding what you’re working toward, and then putting ten pieces in place in order, from a budget and an emergency fund to retirement accounts, investing and a yearly review. Astor is a personal investing agent that helps with the investing steps, because it connects to the accounts you already have, watches what you own and texts you when something matters, and you make every decision.
A plan doesn’t need to be long or perfect. Most people already have the parts, like a paycheck, some savings and a 401(k) at work. What’s usually missing is the order, and the order matters because each step protects the next one.
What is a financial plan?
A financial plan is a written record of where your money is now and what you want it to do, plus the decisions that connect the two. Without one, choices like paying off a card or investing get made by habit.
Where are you starting, and where are you going?
1. Know where you stand
Start with two numbers. Your net worth is everything you own (bank balances, brokerage and retirement accounts, home equity) minus everything you owe. Your monthly cash flow is what comes in minus what goes out. Include subscriptions and irregular costs like car repairs, which is where overspending usually hides. Neither number is a grade. It’s a baseline to measure progress against.
2. Set specific goals
“Save more” isn’t a goal. “Save $15,000 for a down payment by December 2028” is, because it has a number, a date and a purpose, and you can divide it into a monthly amount. Write down at least one short-term goal (one to two years), one medium-term goal (three to seven years) and one long-term goal, usually retirement. Then rank them, so when two goals compete for the same dollar, you already know which wins.
How do you build a base that holds?
3. Make a budget you’ll keep
A budget is a decision about where each paycheck goes. One common rule of thumb is the 50/30/20 split, which puts about half of take-home pay toward needs, 30% toward wants and 20% toward savings and debt payments. Treat it as a starting point, since in an expensive city needs can take more than half. For irregular costs like annual premiums or travel, add up the yearly total, divide by 12 and set that aside each month.
Astor doesn’t do budgeting. A spreadsheet or a budgeting app is the right tool for this step.
4. Build an emergency fund
FINRA notes that financial planners often recommend three to six months of living expenses, and that people with variable income may need more. The CFPB says the right amount depends on your situation and suggests sizing it from the unexpected expenses you’ve actually had. Both say a small fund beats none, and the CFPB calls automatic transfers one of the easiest ways to save consistently.
Keep this money in a savings account at a bank or credit union. FDIC insurance covers $250,000 per depositor, per insured bank, for each account ownership category. It doesn’t cover stocks, mutual funds or crypto, which is one reason emergency money shouldn’t sit in a brokerage account.
5. Pay down high-interest debt
Investor.gov’s advice is to pay down the card with the highest rate first while making minimum payments on the rest, and to treat other debt at about 8% or above the same way. Its reasoning is that no investment strategy pays off as reliably, or with less risk, as clearing high-interest debt.
The CFPB describes two ways to order the payoff. The highest-interest-rate method targets the debt costing you the most, and the snowball method targets the smallest balance first so you see progress sooner. The first usually costs less in interest, and the second can be easier to stick with, so pick the one you’ll keep doing.
How should you save for retirement and invest?
6. Use tax-advantaged accounts in order
One common order is to contribute to your 401(k) at least up to the employer match, then fund an IRA, then raise your 401(k) contributions, and only then use a regular taxable brokerage account. If you have a high-deductible health plan, an HSA often fits in that list too. Here are the 2026 limits from the IRS.
| Account (2026) | Limit | Extra if older |
|---|---|---|
| 401(k) employee contributions | $24,500 | $8,000 at 50+, or $11,250 at ages 60 to 63 |
| IRA (traditional and Roth combined) | $7,500 | $1,100 at 50+ |
| HSA, self-only coverage | $4,400 | $1,000 at 55+ |
| HSA, family coverage | $8,750 | $1,000 at 55+ |
Roth and traditional accounts differ in when you pay tax. Roth contributions go in after tax and qualified withdrawals come out tax-free, while traditional contributions may be deductible now and are taxed later. In 2026, Roth IRA eligibility phases out between $153,000 and $168,000 of income for single filers and between $242,000 and $252,000 for married couples filing jointly. Which fits depends on your tax situation, and a tax professional can help. Check IRS.gov for 2027 limits once they’re announced.
7. Invest by time horizon and risk tolerance
Investor.gov’s guide to asset allocation says the right mix of stocks, bonds and cash depends mostly on how long until you need the money and how much loss you can tolerate. If a sharp drop would push you to sell, a more conservative mix may fit better than one that looks good on paper.
The same guide says to diversify both between asset categories and within them, and to check that your funds don’t mostly own the same companies. It describes rebalancing either on a schedule, such as every six or 12 months, or when an allocation drifts past a set percentage. After that, the ongoing work is knowing what you own, including how concentrated you are and what’s happening to the companies in your accounts.
What keeps the plan safe and current?
8. Get the right insurance
Insurance protects every other step. Health insurance comes first. Disability coverage is easy to overlook, but your paycheck funds everything else in the plan, so check what your employer provides. Renters or homeowners insurance covers your belongings and liability, and term life insurance matters once someone depends on your income. Review coverage after a new job, a move, marriage or a child.
9. Pick tools that fit each step
No single app covers a whole plan, Astor included. A budgeting app or spreadsheet handles steps 3 and 4, your employer’s plan site handles contributions, and for step 7 a personal investing agent can keep watch over what you own between reviews. Add a tool only when a step keeps slipping.
10. Review once a year and after big changes
Once a year, compare your net worth with last year, check each goal, and confirm your budget and investment mix still fit. Revisit the plan right away after a new job, marriage, a child, a home purchase or an inheritance. Most years, the review is a small adjustment rather than a rebuild.
When does working with a CFP professional make sense?
Plenty of people build a solid first plan on their own, especially with a salary, common debts and standard retirement accounts. A CERTIFIED FINANCIAL PLANNER professional is worth it when your situation has more moving parts, such as equity compensation, a business, an inheritance, a divorce, or tax and estate questions. It’s also the right call if you’d rather have a person build the whole plan with you.
You can confirm a certification with the CFP Board’s lookup tool and look up an adviser on the SEC’s Investment Adviser Public Disclosure site. Investor.gov notes that investment advisers are required to act in your best interest.
Where does Astor fit in a financial plan?
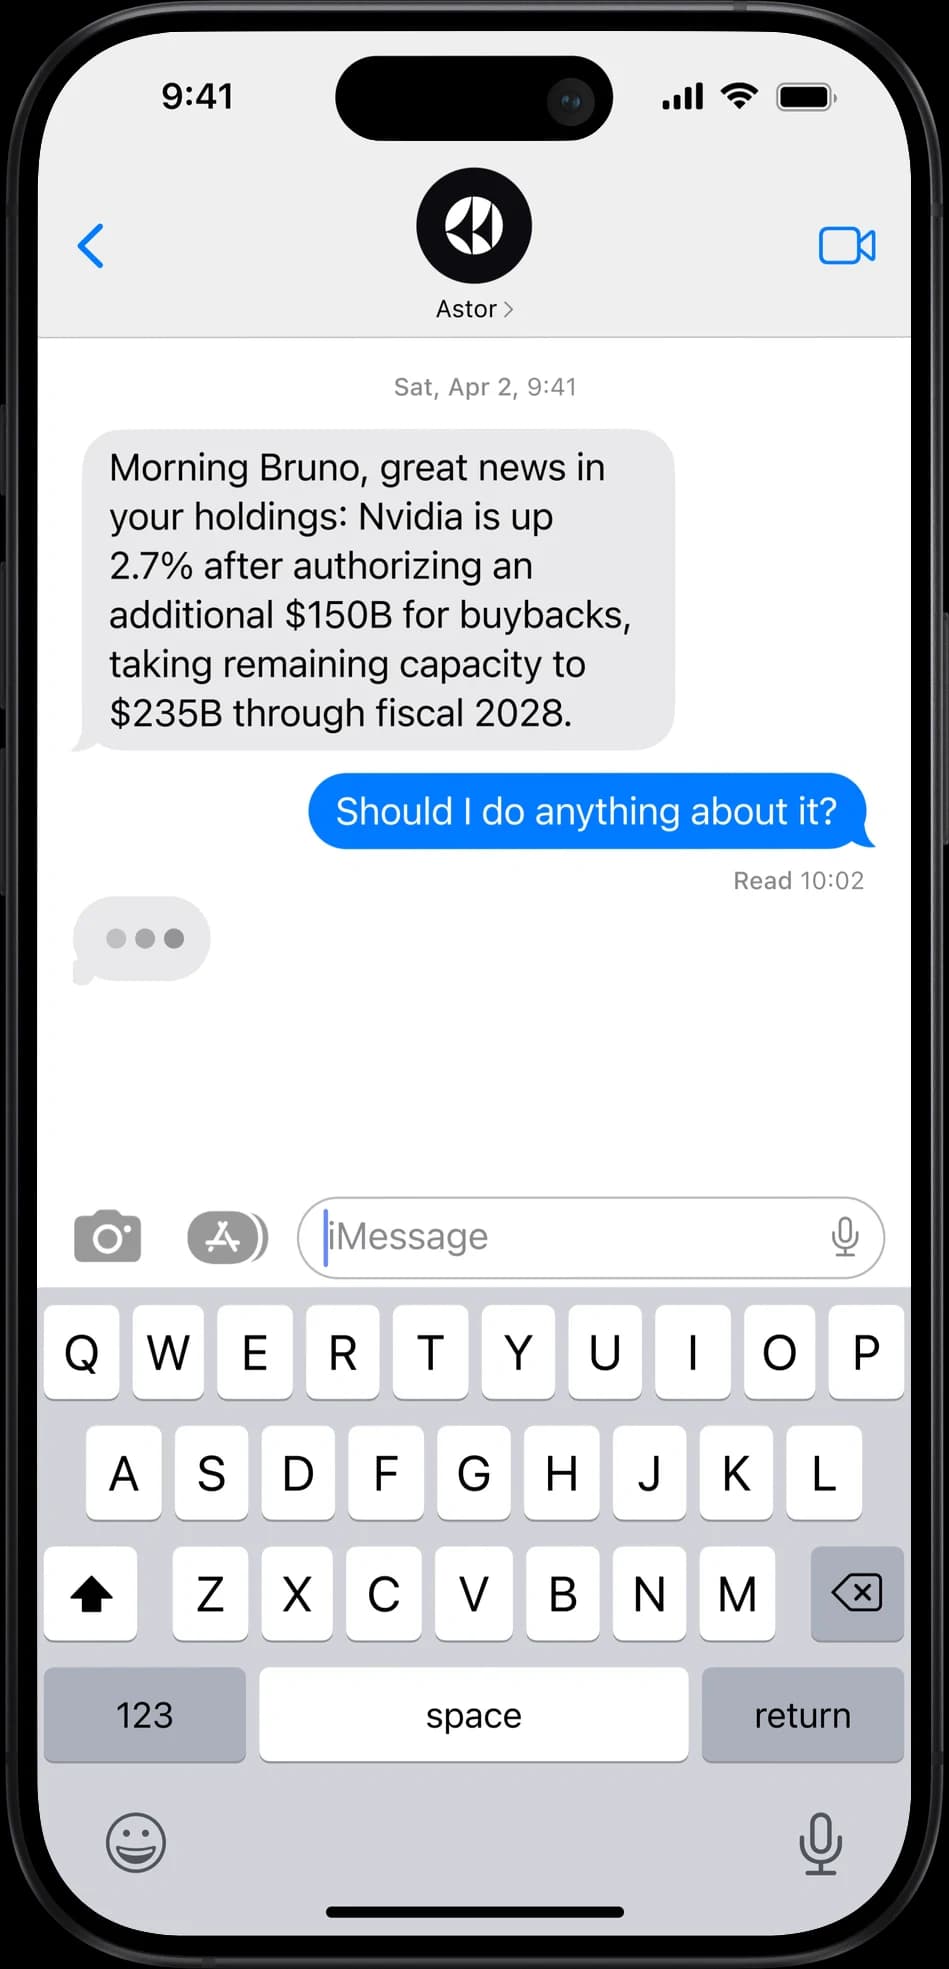
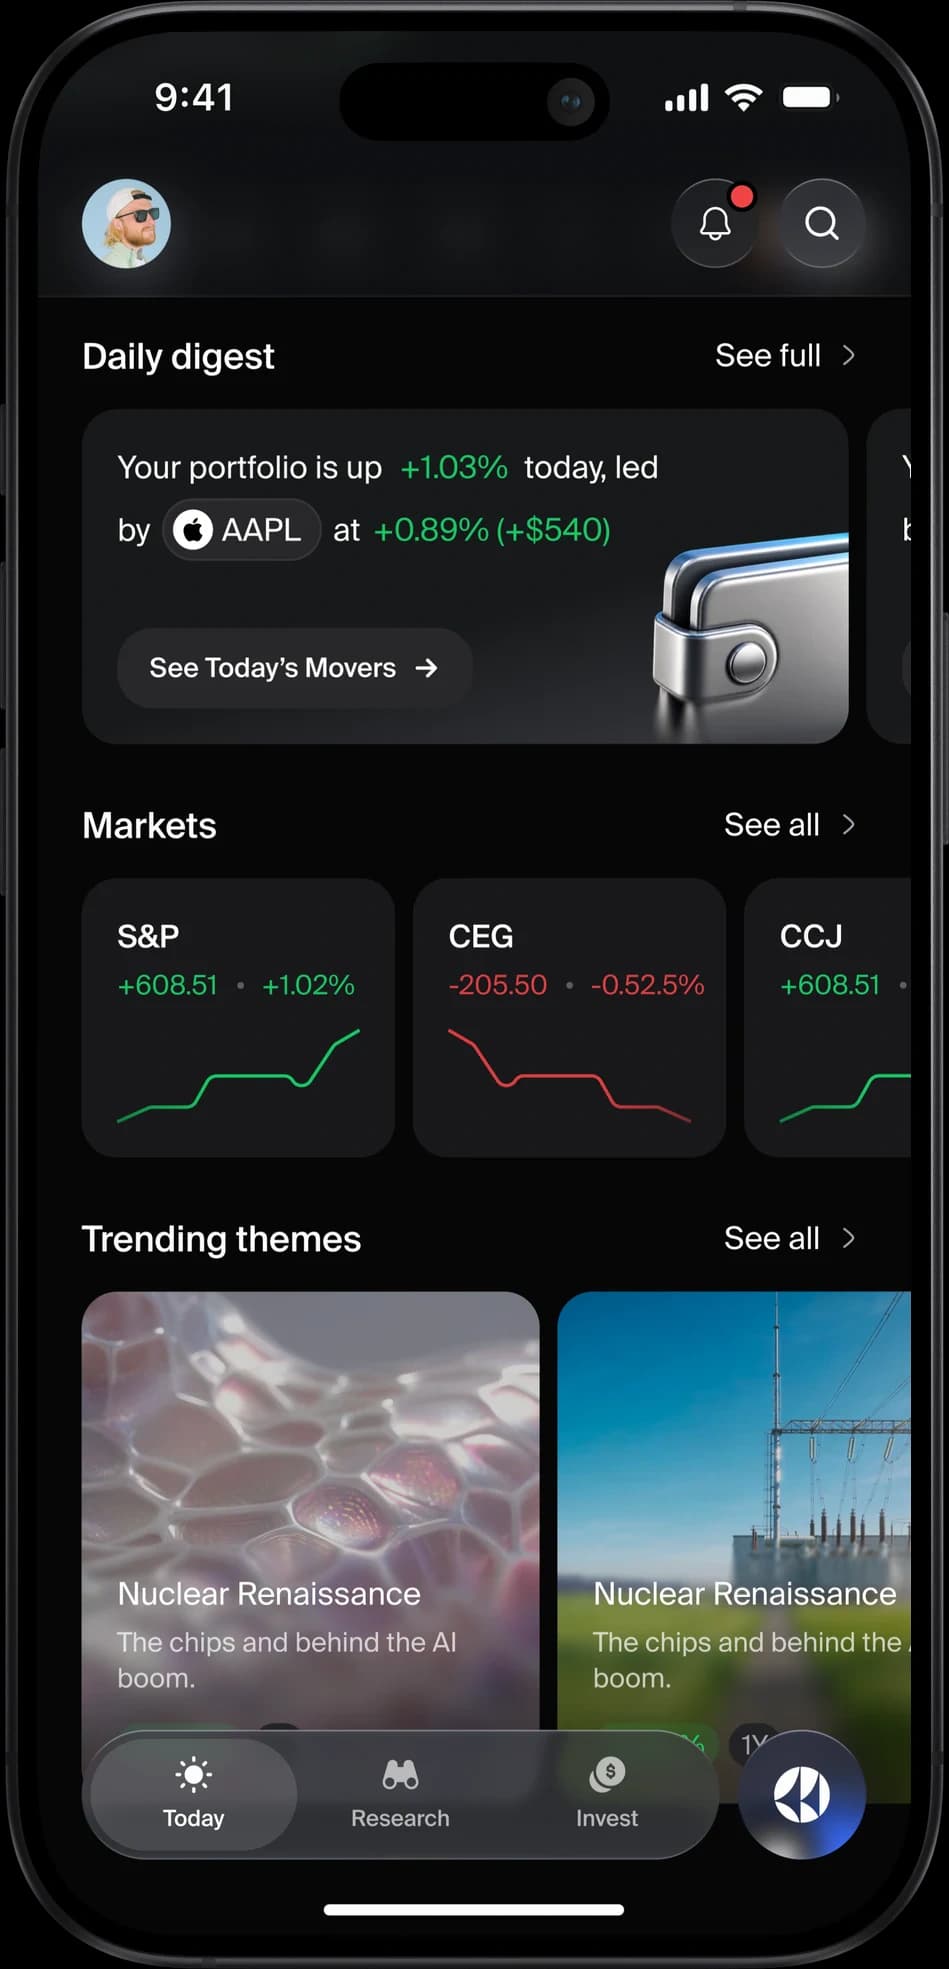
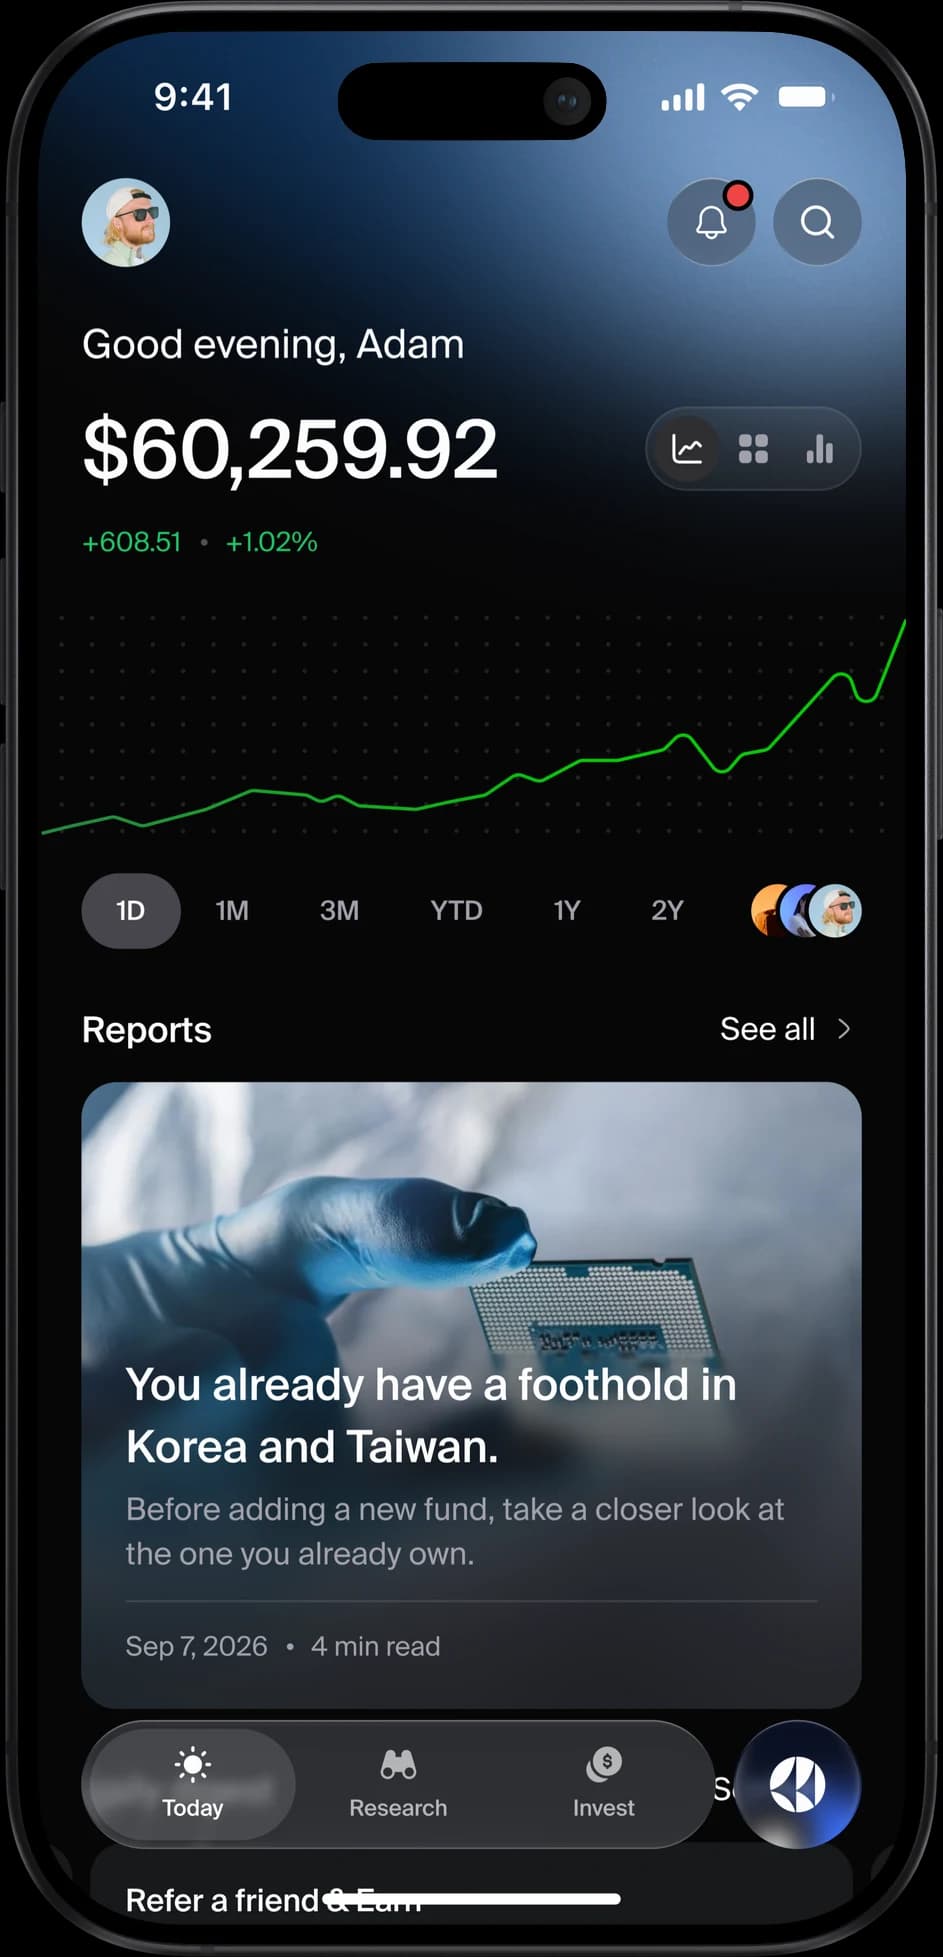
Astor fits steps 7 and 10, the investing and the ongoing review. It’s a personal investing agent on iPhone and in iMessage that connects through Plaid to brokerage, retirement and crypto accounts at most major US institutions, such as Robinhood, Schwab and Coinbase. It can see your holdings, it can’t move money, and you don’t transfer anything to Astor. More in is it safe to connect your brokerage account.
Astor follows every position you own and the earnings dates, filings and headlines that touch them, texts you when something crosses a line you care about, and stays quiet when nothing matters. With scheduled alerts, you can ask it to check something every morning, weekly, before a company reports, or when a condition is met, which helps between yearly reviews. The free plan includes one custom alert. Every alert links to the reasoning and sources behind it, and you make every decision.
Astor doesn’t do budgeting, tax filing or estate planning, doesn’t hold your money and doesn’t run a managed portfolio. The AI can be wrong, which is why it shows its sources and leaves the call to you. Gaus, Inc. DBA Astor is an SEC-registered investment adviser (CRD #338424). Astor is free to start and available in the US only, and you can see how it works.
Frequently asked questions
How long does it take to create a financial plan?
A first version, with your net worth, written goals, a budget, and a debt and savings plan, can come together in a weekend. It doesn’t need to be complete to be useful, and you can add detail at each yearly review.
Do I need a financial adviser to create a financial plan?
Not always. Many people with a salary, common debts and standard retirement accounts build a workable plan on their own. A CFP professional makes sense when your situation is more complex, or when you’d prefer a person to build the plan with you.
How much should I keep in an emergency fund?
FINRA says financial planners often recommend three to six months of living expenses, and more if your income varies. The CFPB says the right amount depends on your situation. Keep it in an insured bank or credit union account, not invested.
What’s the difference between a budget and a financial plan?
A budget decides where each month’s income goes. A financial plan is the bigger picture the budget serves, covering your goals, emergency fund, debt, retirement savings, investments, insurance and a regular review.
Sources
- IRS: 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 (IR-2025-111, Nov. 13, 2025), accessed Oct 21, 2026
- IRS: Publication 969 (2025), Health Savings Accounts and Other Tax-Favored Health Plans, accessed Oct 21, 2026
- FINRA: Financial Foundations (emergency fund), accessed Oct 21, 2026
- CFPB: An essential guide to building an emergency fund, accessed Oct 21, 2026
- FDIC: Understanding Deposit Insurance, accessed Oct 21, 2026
- Investor.gov (SEC): Pay Off Credit Cards or Other High Interest Debt, accessed Oct 21, 2026
- CFPB: How to reduce your debt, accessed Oct 21, 2026
- Investor.gov (SEC): Beginners’ Guide to Asset Allocation, Diversification, and Rebalancing, accessed Oct 21, 2026
- Investor.gov (SEC): Investment Advisers, accessed Oct 21, 2026
- CFP Board: Verify a CFP Professional, accessed Oct 21, 2026
- SEC Investment Adviser Public Disclosure: Astor (CRD 338424), accessed Oct 21, 2026
Important information
Gaus, Inc. DBA Astor is an SEC-registered investment adviser (CRD #338424). Registration does not imply a certain level of skill or training. Astor provides non-discretionary advice: you make every investment decision. All investing involves risk, including the loss of principal, and past performance does not guarantee future results. Astor uses AI, which can make mistakes. This article is general information, not individualized investment, tax or legal advice. See our disclosures.
About comparisons
Information about other companies comes from their public websites and filings as of October 2026 and may have changed since; check each provider for current details. Comparisons and rankings reflect Astor’s opinion. Other companies’ names and trademarks belong to their owners, and no affiliation or endorsement is implied.
Share