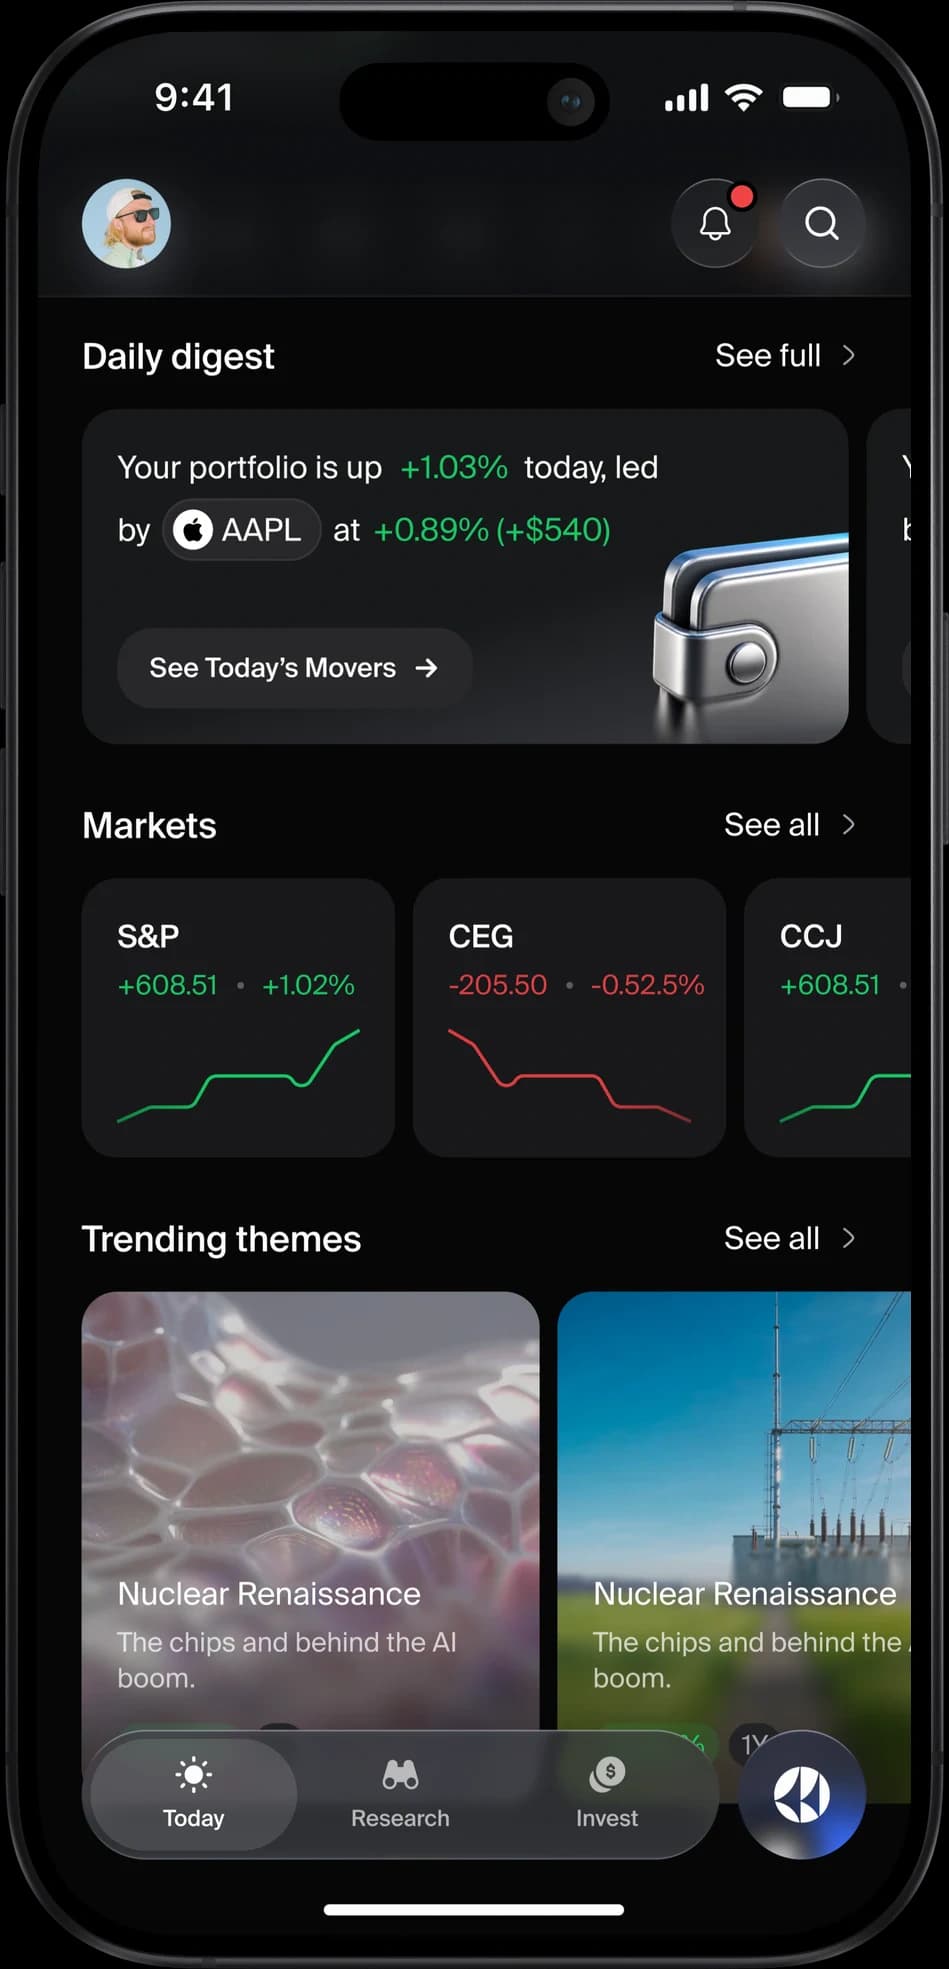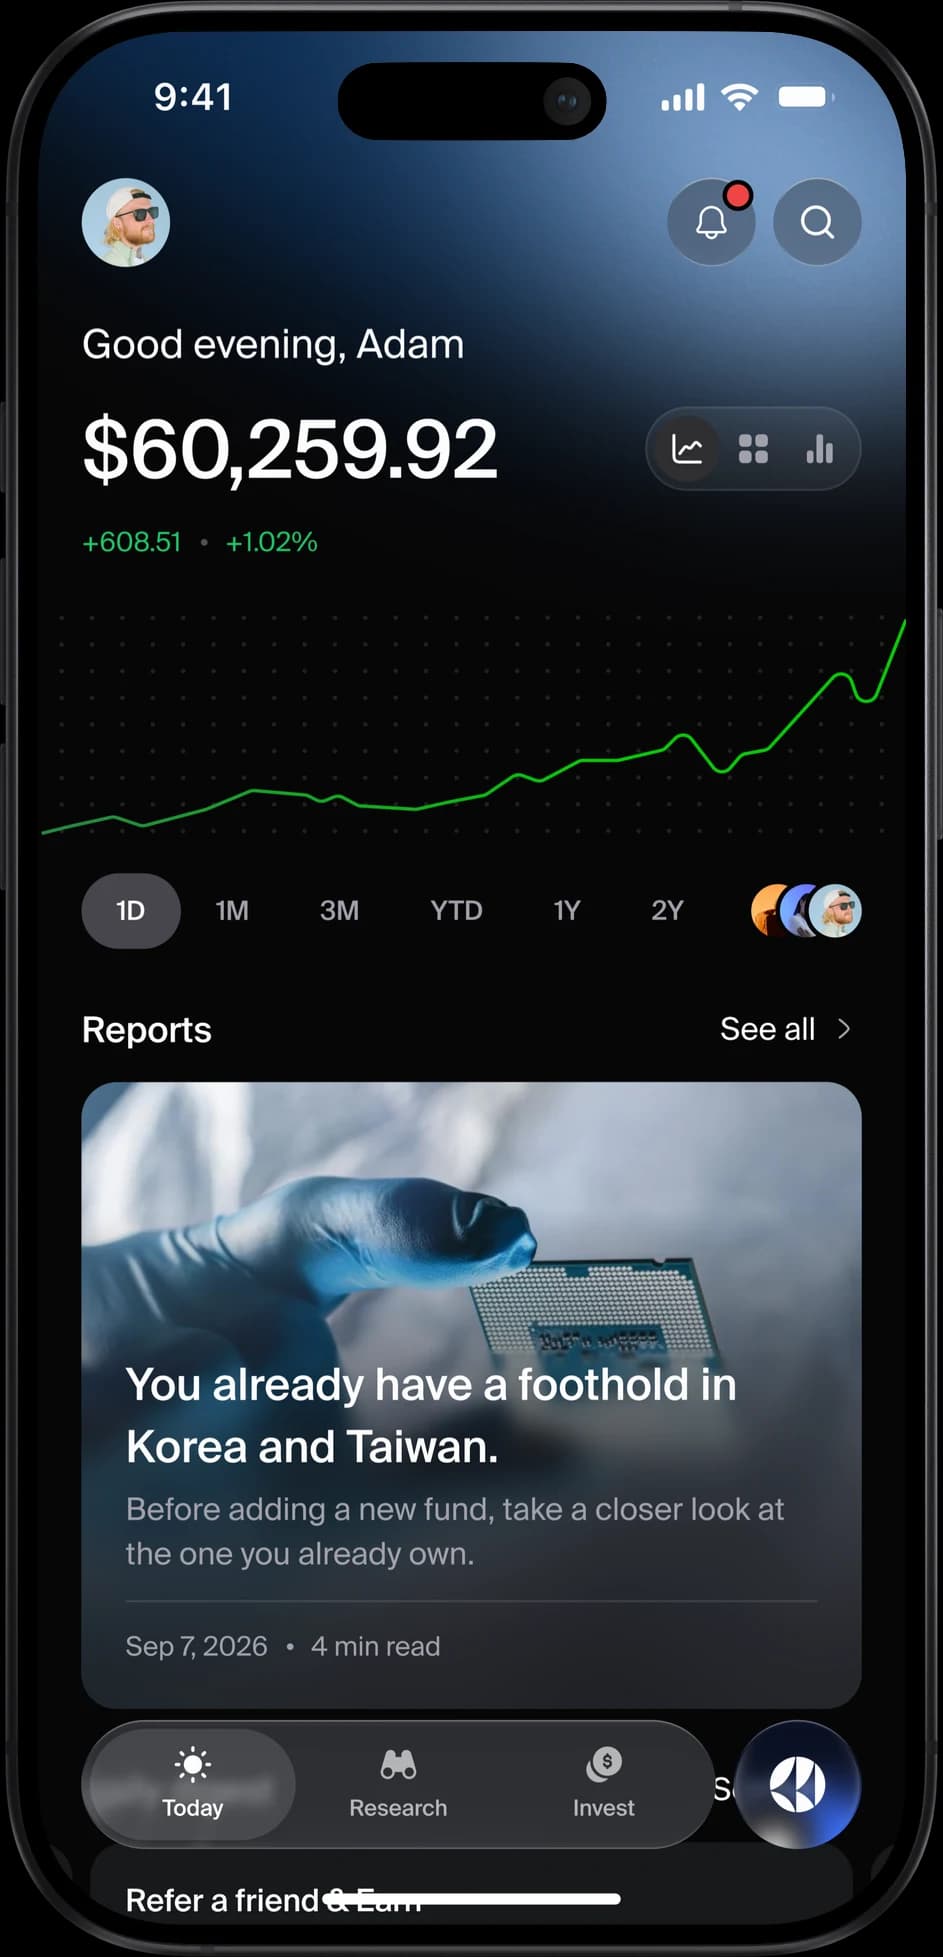
To review your investment portfolio, put every account you own into one list, then check your mix of stocks, bonds and cash, how much rides on any one company or sector, what you pay in fees, and whether it all still fits your goals. Change something only if it has drifted from what you intended. Astor is a personal investing agent that connects all your accounts in one place, which takes care of the hardest step, and watches what you own between reviews while you make every decision.
A review isn’t a rebuild. It’s a structured check-in that usually takes an hour or two, and often the right outcome is a small adjustment or none at all.
How often should you review your portfolio?
In our view, a full review once a year is enough for most people, plus an extra one when your life changes. A new job, a big raise, a marriage, a child, a home purchase or a windfall can each change what your money is for, which is a better reason to revisit your plan than anything the market did last month.
This lines up with how the SEC’s Investor.gov describes rebalancing. It says many financial experts recommend doing it on a regular interval, such as every six or twelve months, and that rebalancing tends to work best when done relatively infrequently. Looking at your accounts more often is fine, as long as you keep looking separate from acting. Our guide on time in the market vs. timing the market covers why reacting to every move can be costly.
What should you gather before you start?
Every account, in one list. You can’t judge a portfolio you can only see in pieces.
- Your current employer’s 401(k) or 403(b)
- Old 401(k)s from previous jobs, which are easy to forget
- Roth or traditional IRAs
- An HSA, if you’ve invested it
- Taxable brokerage accounts
- Vested company stock, RSUs or ESPP shares
- Crypto accounts
For each one, write down the institution, the account type, the balance and what it holds. Every other step depends on this list, because a fund that looks sensible in one account can double up on something you already own in another.
Is your mix of stocks, bonds and cash still right?
Your asset allocation is how your money is divided among stocks, bonds and cash, measured across your entire portfolio rather than account by account. Investor.gov says the right mix depends largely on your time horizon and your ability to tolerate risk, and that there’s no single model that’s right for every goal.
Add up each category across all your accounts and compare the result with what you intended. If you never set a target, this is the time to pick one. Two checks help.
- Does it match your timeline? Money for a goal decades away can usually take more ups and downs than money you’ll need in a couple of years. Investor.gov says a portfolio heavily weighted in stocks would be inappropriate for a short-term goal, and it also notes that cash carries inflation risk, the risk that rising prices erode what your money can buy.
- Could you live with it in a bad year? If a sharp drop in your stocks would make you sell, the mix is probably more aggressive than you can actually hold.
Then step back and ask whether your goals themselves have changed. Investor.gov says the most common reason to change your allocation is a change in your time horizon, and that a change in your risk tolerance, financial situation or goal is a reason too. A recent rally or slump in one asset class isn’t on that list.
Are you too concentrated in one company or sector?
Concentration is when too much of your portfolio depends on one position or one industry.
Single companies
If you work at a public company, vested RSUs and ESPP shares can quietly become your largest holding, on top of the paycheck that already depends on the same company. Look at what share of your total portfolio each individual stock represents, and decide in advance how large you’re willing to let any one position get. Investor.gov notes that a stock portfolio isn’t diversified if it holds only four or five individual stocks.
Sectors and overlapping funds
Funds can concentrate you too. Investor.gov points out that a fund focused on one industry sector doesn’t give you instant diversification. Owning several broad US stock funds that track similar indexes can also mean owning many of the same large companies two or three times. Open each fund’s top holdings and see how much they overlap.
What are you paying in fees and taxes?
Fees
Fees are easy to ignore because each one is small, but they come out every year. Investor.gov illustrates this with a hypothetical $100,000 investment growing 4% a year for 20 years, which ends at about $208,000 with a 0.25% annual fee and about $179,000 with a 1.00% fee. That’s the SEC’s illustration, not a forecast, but it shows why fees deserve a line in your review.
List the expense ratio of every fund you own and any advisory or account fees on top. FINRA’s Fund Analyzer lets you look up and compare fund costs. If you hold an expensive fund without a clear reason, ask whether a cheaper one would do the same job. Investor.gov also suggests asking any professional you pay how they’re paid, whether by commission, by the amount of assets they manage, or another way.
Taxes
Where you hold something can matter too. Retirement accounts like 401(k)s and IRAs have different tax treatment from a taxable brokerage account, so many investors think about which holdings belong in which kind of account. Before you sell anything in a taxable account, check whether the sale would trigger capital gains. This is general education, not tax advice, and a tax professional can tell you what makes sense for your situation.
When should you rebalance, and how?
Rebalance when your mix has drifted far enough from your target that it no longer carries the risk you chose. Investor.gov gives the example of a portfolio meant to be 60% stocks that drifts to 80% after a stock market rise. It describes three ways to bring it back.
- Sell some of what’s overweight and use the money to buy what’s underweight.
- Buy more of the underweight asset with new money.
- If you’re contributing regularly, point new contributions at the underweight category until things are back in balance.
Investor.gov also says to consider whether your rebalancing method will trigger transaction fees or taxes before you start. That’s one reason to start with retirement accounts or with new contributions before selling anything in a taxable account.
A few common mistakes are worth checking for while you’re here.
- Forgotten old 401(k)s. They can sit for years in whatever default investments they started with. Decide whether to leave them, move them to your current plan, or roll them into an IRA.
- Idle cash. Money left in a cash sweep account by accident isn’t part of any plan.
- Selling on recent performance alone. A fund having a weak six months isn’t, by itself, a reason to sell. Judge it on whether it still fits your plan and what it costs.
How Astor fits into a portfolio review
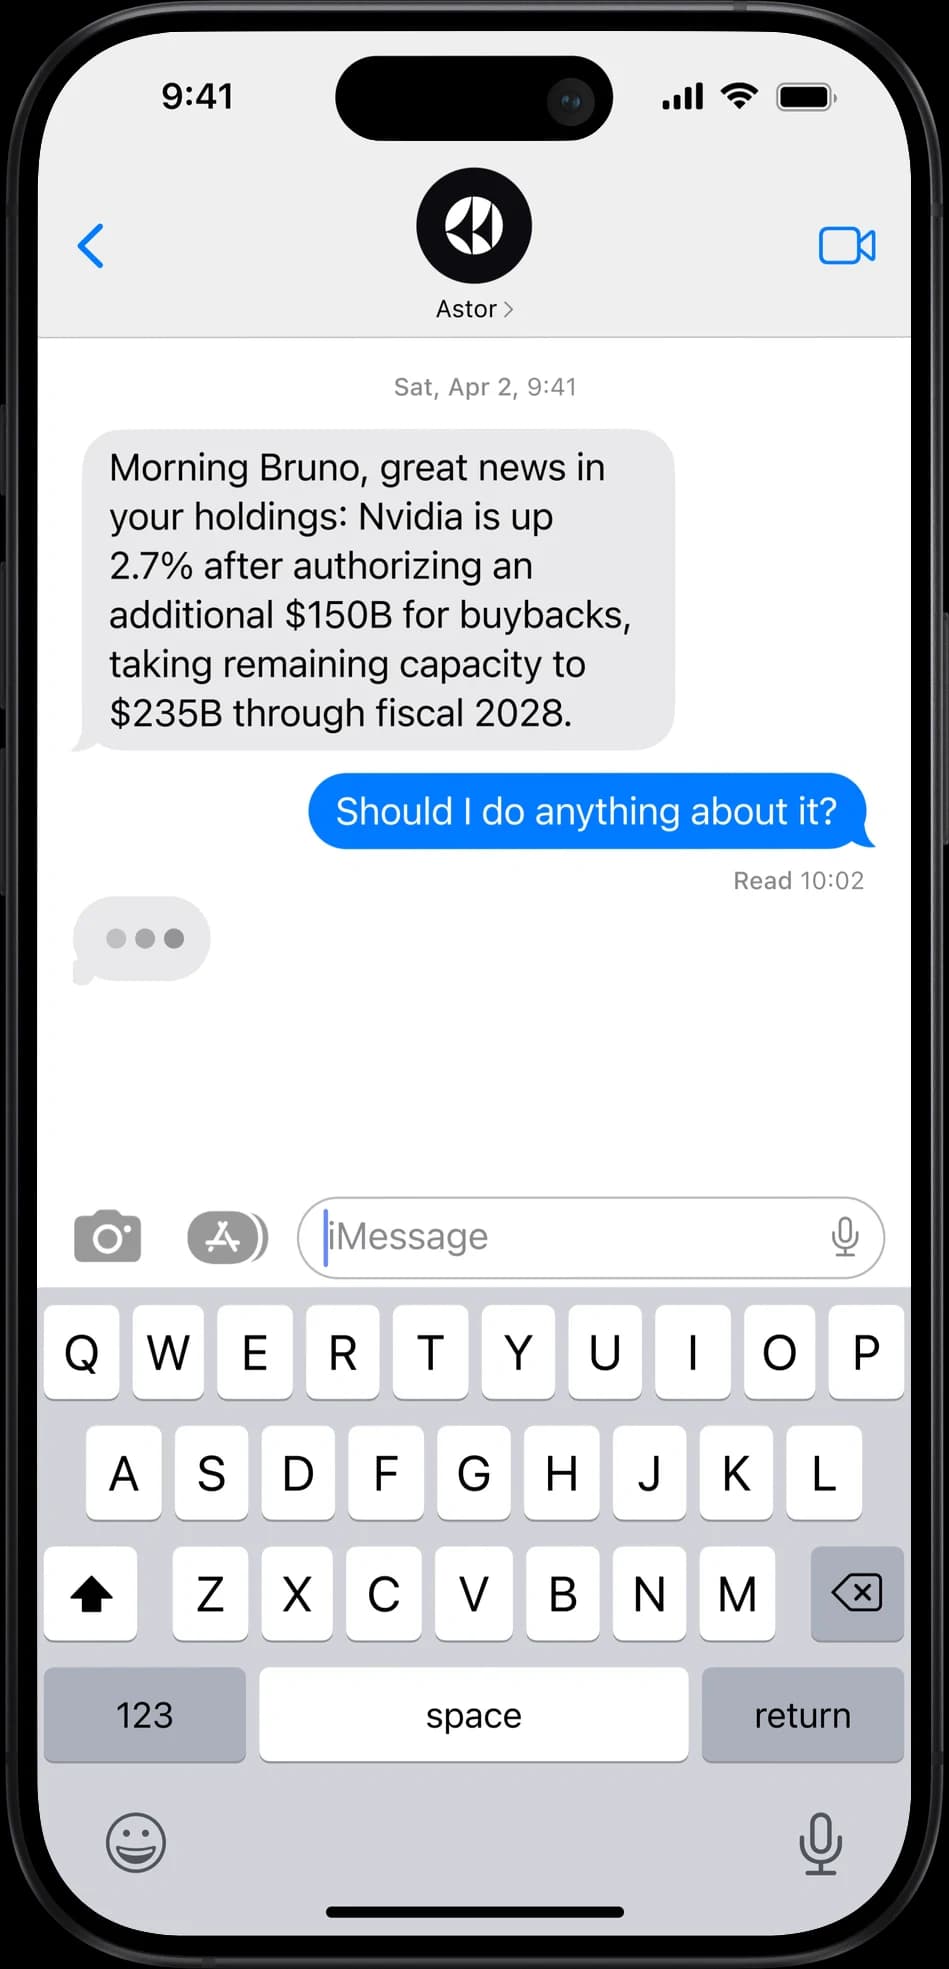
Astor is a personal investing agent on iPhone and in iMessage. It connects to brokerage, retirement and crypto accounts at most major US institutions, such as Robinhood, Schwab and Coinbase, through Plaid, so the first step of a review, getting your accounts into one picture, is done once instead of every year. Astor can see your holdings but can’t move money, and you don’t transfer anything to it.
Between reviews, Astor follows every position you own and the earnings dates, filings and headlines that touch them, and texts you when something crosses a line you care about. At a glance gives you a five-second daily check with two lines on what moved your money today and why. Themes let you group what you own, like AI infrastructure or nuclear power, and follow each group, which can help you notice when several holdings ride on the same idea. With scheduled alerts, you can ask Astor to check something on a schedule, like every Monday morning or before a company you own reports, and the free plan includes one custom alert. You can also ask Astor questions about your actual holdings in the app or in iMessage.
Astor doesn’t rebalance, trade or decide anything in your connected accounts, and it doesn’t do tax filing or estate planning. The AI can be wrong, which is why it shows its sources. You make every decision. Astor is free to start and available in the US only, and you can see how it works.
Frequently asked questions
How often should I review my investment portfolio?
In our view, once a year is enough for most people, plus an extra review after a major life change like a new job, a marriage or a home purchase. Investor.gov notes that many experts recommend rebalancing every six or twelve months, and that rebalancing tends to work best when done relatively infrequently.
Do I need a financial advisor to review my portfolio?
Not for a basic review. Listing your accounts, checking your mix, concentration and fees, and rebalancing are things many people can do themselves. A financial professional can add real value in more complex situations, like large amounts of company stock, retirement income planning, or tax and estate questions.
Should I sell something just because it dropped?
Not on price alone. A better test is whether the holding still fits your plan, whether it costs more than it should, and whether it leaves you more concentrated than you want. A drop can be a reason to look closer, but it isn’t a decision by itself.
What should I fix first if my review finds several problems?
Prioritize. In our view, concentration you didn’t intend usually deserves attention first, then high fees, then any drift in your overall mix. Check the tax cost of each change before selling in a taxable account.
Sources
- Investor.gov (SEC): Beginners’ Guide to Asset Allocation, Diversification, and Rebalancing, accessed Oct 21, 2026
- Investor.gov (SEC): Understanding Fees, accessed Oct 21, 2026
- FINRA: Fund Analyzer, accessed Oct 21, 2026
Important information
Gaus, Inc. DBA Astor is an SEC-registered investment adviser (CRD #338424). Registration does not imply a certain level of skill or training. Astor provides non-discretionary advice: you make every investment decision. All investing involves risk, including the loss of principal, and past performance does not guarantee future results. Astor uses AI, which can make mistakes. This article is general information, not individualized investment, tax or legal advice. See our disclosures.
About comparisons
Information about other companies comes from their public websites and filings as of October 2026 and may have changed since; check each provider for current details. Comparisons and rankings reflect Astor’s opinion. Other companies’ names and trademarks belong to their owners, and no affiliation or endorsement is implied.
Share